How to Insure Farm Machinery Shared Between Neighbouring Farmers in Kenya
Quick answer
Ensure all co-owners are named on the policy as co-insured parties, get geographic coverage across all farms where equipment will be used, include approved operators beyond just one person, and add third-party liability cover protecting all co-owners. Work with an independent broker to find insurers flexible with cooperative arrangements, and create a written sharing agreement covering ownership percentages, cost sharing, and claim procedures.
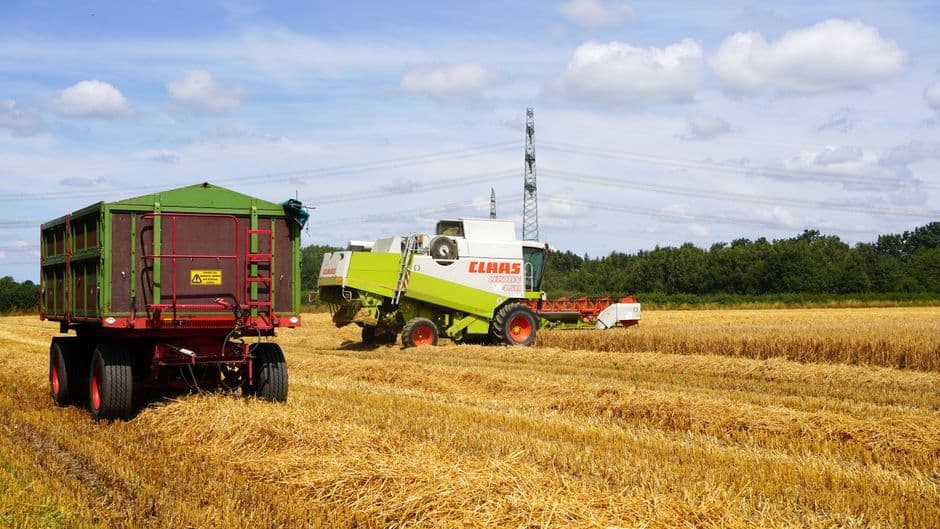
Picture this: You and three neighbouring farmers in Nakuru have just pooled funds to buy a tractor worth Ksh 2.5 million. It's a game-changer — what used to take weeks of manual labour now takes days. The tractor moves from your shamba to Kamau's, then to Wanjiku's, and finally to Omondi's during planting and harvesting seasons. Everyone contributes to fuel and maintenance. But then one afternoon, while ploughing Kamau's field, the tractor hits a hidden rock and the engine seizes. The repair bill? Ksh 400,000. Who pays?
This is the reality for many Kenyan farmers who share expensive farm machinery. It makes perfect financial sense to pool resources — a single smallholder can rarely justify owning a Ksh 2 million harvester that sits idle most of the year. But when something goes wrong, the lack of clear insurance arrangements can turn friendly neighbours into bitter disputants.
Let's break down what you need to know about insuring shared farm equipment, and how to protect everyone's investment without creating conflict.
Why Standard Insurance Arrangements Don't Work for Shared Machinery
Most farm equipment insurance policies are designed with a simple assumption: one owner, one farm, one location. But when machinery moves between multiple farms and is operated by different people, several complications arise:
The ownership question: Insurance policies need to name a policyholder. If the tractor is registered in Kamau's name but owned jointly by four farmers, what happens when Wanjiku is using it and there's an accident? Will the insurer pay out? Will Kamau be personally liable?
The location issue: Many agricultural insurance policies have geographic limits. Your policy might cover the tractor while it's on your farm in Molo, but what happens when it's being transported to a neighbour's farm 15 kilometres away in Elburgon?
The operator problem: Who's allowed to drive or operate the machinery? If your policy only covers you as the named operator, but your neighbour's son is the one actually driving during harvest, you could find your claim rejected.
These aren't small technicalities — they're the kinds of gaps that leave farmers facing huge bills when things go wrong.
Key Insurance Considerations for Shared Farm Equipment
When you're setting up a sharing arrangement for tractors, harvesters, ploughs, or other expensive machinery, here are the critical insurance elements to address:
1. Named Parties and Joint Ownership
Your insurance policy needs to clearly reflect the actual ownership structure. If four farmers have contributed equally, all four should ideally be named on the policy as co-insured parties (people who are covered by the insurance). This ensures that no matter who's using the equipment when damage occurs, everyone's protected.
Different insurers handle joint ownership differently — some are comfortable with multiple named insured parties, while others prefer a single policyholder with additional users listed. This is where working with an independent broker like Vike Insurance makes a real difference. We can compare policies across the market and identify which insurers offer the most flexible arrangements for shared ownership, ensuring your specific setup is properly covered.
2. Geographic Coverage
Make sure your policy covers the equipment across all the farms where it will be used, not just one location. This is called 'territorial limits' in insurance language — basically, the geographic area where your cover applies.
You'll also want coverage during transit between farms. If the tractor is being transported on a lorry from one shamba to another and there's an accident, you need to know you're covered.
3. Approved Operators
Be clear about who's allowed to operate the machinery. Some policies will cover 'any competent operator', while others require you to name specific people. Given that shared equipment will naturally be used by different farmers and their workers, you need a policy that's flexible enough to accommodate this reality.
Consider whether operators need to have specific training or licenses. For very expensive equipment, some insurers may require proof that operators have been trained, which is actually good practice anyway.
4. Maintenance and Condition Requirements
Insurers typically require that machinery is properly maintained. When equipment is shared, it's essential to agree among yourselves who's responsible for routine maintenance, servicing schedules, and keeping service records.
Your insurance policy might require regular servicing by qualified mechanics. Make sure you understand these requirements and that all co-owners are committed to meeting them — because if you skip servicing to save money and then have a breakdown, your claim could be denied.
5. Liability Cover
This is crucial and often overlooked. If the shared tractor injures someone or damages someone else's property while being operated by one of the co-owners, who's liable? You need third-party liability cover (insurance that pays for damage or injury you cause to others) that protects all the co-owners, not just the named policyholder.
6. Agreed Value and Depreciation
When you take out the policy, establish an 'agreed value' — the amount the insurer will pay if the equipment is completely destroyed or stolen. This should reflect the current market value and be agreed upon by all co-owners.
Remember that farm machinery depreciates (loses value) over time. Review the insured value annually to make sure it still reflects reality. You don't want to be paying premiums based on a Ksh 2.5 million value when the tractor is now only worth Ksh 1.8 million — but equally, you don't want to discover you're underinsured when you need to replace it.
Creating a Sharing Agreement
Beyond insurance, it's wise to create a simple written agreement among the co-owners covering:
- Each person's ownership percentage
- How costs (insurance, fuel, repairs, servicing) will be shared
- A usage schedule or booking system
- What happens if someone wants to exit the arrangement
- How insurance claims will be handled
This doesn't need to be complicated or expensive — a simple written agreement witnessed by a local chief or elder can prevent enormous headaches later.
Why Independent Advice Matters
The Kenyan insurance market offers very different approaches to shared agricultural equipment. Some insurers are flexible and experienced with cooperative arrangements; others have rigid policies designed for single owners. Premium rates vary significantly, as do the exclusions (situations where the policy won't pay) and claim settlement processes.
As an independent broker, Vike Insurance isn't tied to any single insurance provider. We work for you, not the insurer. That means we can compare policies across the whole market, identify which providers offer the most suitable cover for shared machinery arrangements, and negotiate on your behalf to get comprehensive protection at a fair price.
We understand the Kenyan agricultural context — the realities of smallholder farming, the importance of cooperative arrangements, and the unique risks you face. We'll explain the policy terms in plain language, help you understand exactly what's covered and what's not, and make sure there are no nasty surprises when you need to make a claim.
Ready to Protect Your Shared Investment?
Sharing farm machinery is smart economics — but only if everyone's investment is properly protected. Don't let unclear insurance arrangements turn a good idea into a source of conflict and financial stress.
Get in touch with the team at Vike Insurance for a free, no-obligation consultation. We'll assess your specific sharing arrangement, compare policies across the market, and find cover that protects all co-owners fairly and comprehensively. Call us today or visit our offices — let's make sure your shared equipment is covered properly, so you can focus on farming, not worrying.
Share this article
See your specialist cover options
Talk to a broker about cover built for your specific risk.
Start Free Quote →Frequently asked questions
What happens if shared farm equipment is damaged while being used by one of the co-owners?
Does farm equipment insurance cover machinery when it moves between different farms?
Who is liable if shared farm machinery injures someone or damages property?
Can insurance claims be rejected on shared farm equipment?
Should farmers create a written agreement for shared farm machinery?
Related Content
 specialist cover
How Agricultural Insurance Can Protect Your Irrigation Equipment and Keep Your Farm Productive
Read → specialist cover
Event and Wedding Insurance in Kenya: Protecting Your Big Day from the Unexpected
Read → specialist cover